Chargeback Prevention Tools and Service
Chargebacks cost you the sale, the product and a fee, and a rising ratio can put your merchant account at risk. SwissPay gives you real-time fraud scoring, 3-D Secure 2 where required, and chargeback and PayPal dispute handling with automated evidence submission.
Chargeback prevention is the practice of stopping disputes before they post, using real-time fraud scoring, 3-D Secure 2 and clear billing descriptors to resolve issues at the source. SwissPay provides real-time fraud scoring and 3-D Secure 2 where required, plus chargeback and PayPal dispute handling with automated evidence submission for the disputes that still post.
What is chargeback prevention?
Chargeback prevention is the set of tools and practices that stop a card dispute before it becomes a formal chargeback. It combines real-time fraud scoring, 3-D Secure 2 authentication, clear billing descriptors and prompt customer service, so a would-be dispute is refunded or resolved at the source rather than posting against the merchant.
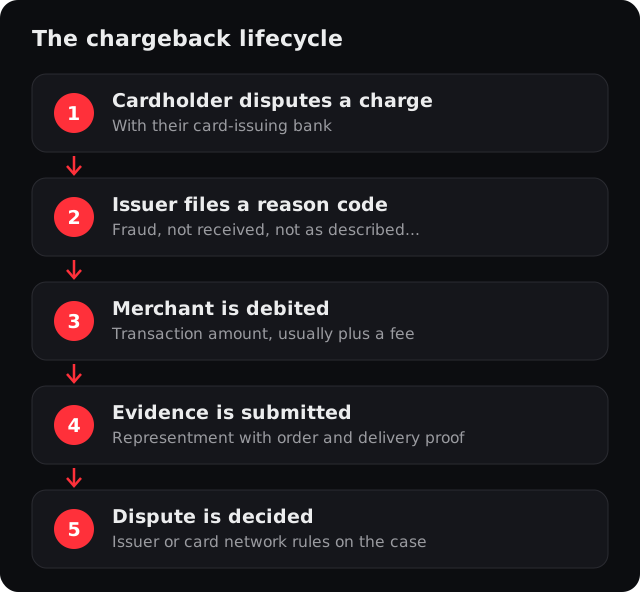
A chargeback happens when a cardholder disputes a transaction with their issuing bank rather than the merchant. Prevention works upstream of that. Real-time fraud scoring uses AVS, device and risk signals to block risky orders before they settle. Authentication with 3-D Secure 2 shifts liability for many fraud claims to the issuer, and an accurate billing descriptor cuts the disputes from customers who do not recognize a charge, the kind that drive friendly fraud. When a dispute still lands, chargeback and PayPal dispute handling steps in with automated evidence submission.
How does SwissPay's chargeback prevention work?
SwissPay layers prevention into the payment flow. Real-time fraud scoring screens orders using AVS, device and risk signals, 3-D Secure 2 authenticates cardholders where required and can shift fraud liability, and chargeback and PayPal dispute handling submits evidence automatically when a dispute posts. Clear descriptors and prompt refunds remain your job.
Real-time fraud scoring
Screens each order using AVS, device and risk signals to block or flag high-risk transactions before they settle.
3-D Secure 2
Authenticates the cardholder at checkout where required, in frictionless and challenge flows, and can move liability for authenticated fraud to the issuing bank.
Chargeback and PayPal dispute handling
Manages disputes across both card networks and the PayPal wallet, with automated evidence submission to contest illegitimate claims.
Accurate billing descriptors
A descriptor customers recognize cuts the unrecognized-charge disputes behind much friendly fraud.
Who needs chargeback prevention?
Any business exposed to disputes benefits, but it is critical for subscription and high-volume merchants: subscription and free-trial models, high-ticket sellers, and verticals like nutraceuticals, telehealth, crypto and iGaming. If your chargeback ratio is climbing toward a card-network threshold, prevention is how you protect your merchant account.
Subscription and trial billing
Recurring and free-trial models, where friendly fraud is common.
High-ticket and cross-border
High-ticket items or cross-border sales, where fraud and disputes run higher.
Dispute-prone verticals
Nutraceuticals, health and wellness subscriptions, telehealth, crypto or iGaming.
Rising ratio or monitoring
Your chargeback ratio is rising toward a network threshold, or a processor has placed you in a monitoring program.
Chargeback prevention vs representment: what is the difference?
Prevention stops a dispute before it posts; representment fights one after it does. Prevention uses fraud scoring, 3DS2 and clear descriptors to resolve issues at the source. Representment is the process of contesting a chargeback with compelling evidence to recover the funds. A complete chargeback management program uses both, in that order.
| Representment | Chargeback prevention | |
|---|---|---|
| When it acts | After a chargeback or PayPal dispute posts | Before a chargeback ever posts |
| What it does | Contests the reason code with evidence to reverse the dispute | Fraud scoring, 3-D Secure 2 and clear descriptors resolve issues at the source |
| Effect on your ratio | Recovers revenue on disputes that slip through | A prevented dispute never counts against your ratio |
| Coverage | Card chargebacks and PayPal disputes with automated evidence submission | Card and PayPal-wallet orders screened before they settle |
Chargeback, retrieval request or PayPal dispute: what is the difference?
A chargeback is a reversal the cardholder's bank starts after a dispute. A retrieval request sometimes comes first, when the bank only asks for transaction details. A PayPal dispute opens inside PayPal and can escalate to a claim. Each one needs a fast, documented response with the right evidence.
The deadlines and evidence differ, so treat them separately. A retrieval request is a chance to clear up confusion before money moves. A quick answer with order details, delivery proof and the customer's agreement to your terms often ends it there.
A chargeback debits the transaction amount, usually plus a fee, and you can contest it through representment. A PayPal dispute starts as a conversation between buyer and seller and becomes a claim if it is not resolved. SwissPay handles card chargebacks and PayPal disputes with automated evidence submission.
How do I get started with chargeback prevention?
Submit one application with your business details, vertical and monthly volume. SwissPay boards and underwrites you in-house on PayPal rails, so you do not need your own PayPal account, and the account comes with real-time fraud scoring, 3-D Secure 2 where required and dispute handling. Start at the form or email support@swisspay.ai.
- 1Complete the application
Share your business name, contact, website, vertical and monthly volume.
- 2Get boarded on PayPal rails
SwissPay reviews and underwrites your business in-house, so you do not need your own PayPal account.
- 3Go live
Use a REST API, hosted checkout, or the Shopify and WooCommerce plugins, with real-time fraud scoring and 3-D Secure 2 where required.
- 4Respond to disputes
When a chargeback or PayPal dispute posts, SwissPay handles it with automated evidence submission.
Facing rising chargebacks?
Apply once to get real-time fraud scoring, 3-D Secure 2 where required, and chargeback and PayPal dispute handling on PayPal rails, with card and wallet vaulting for subscriptions and rebills.
Apply nowRelated
Frequently asked questions
What is chargeback prevention?
What is the difference between chargeback prevention and representment?
Does SwissPay handle PayPal disputes as well as card chargebacks?
Does 3-D Secure 2 reduce chargebacks?
What is a chargeback ratio and why does it matter?
Can chargeback prevention guarantee no chargebacks?
Apply for a merchant account
Tell us about your business. One application, boarded and underwritten in-house on PayPal rails, with card and PayPal-wallet processing built for subscriptions.
- Boarded and underwritten in-house, no separate PayPal account needed
- Card and PayPal-wallet vaulting for subscriptions, trials and rebills
- PCI DSS Level 1, 3-D Secure 2 where required, and chargeback and dispute handling built in